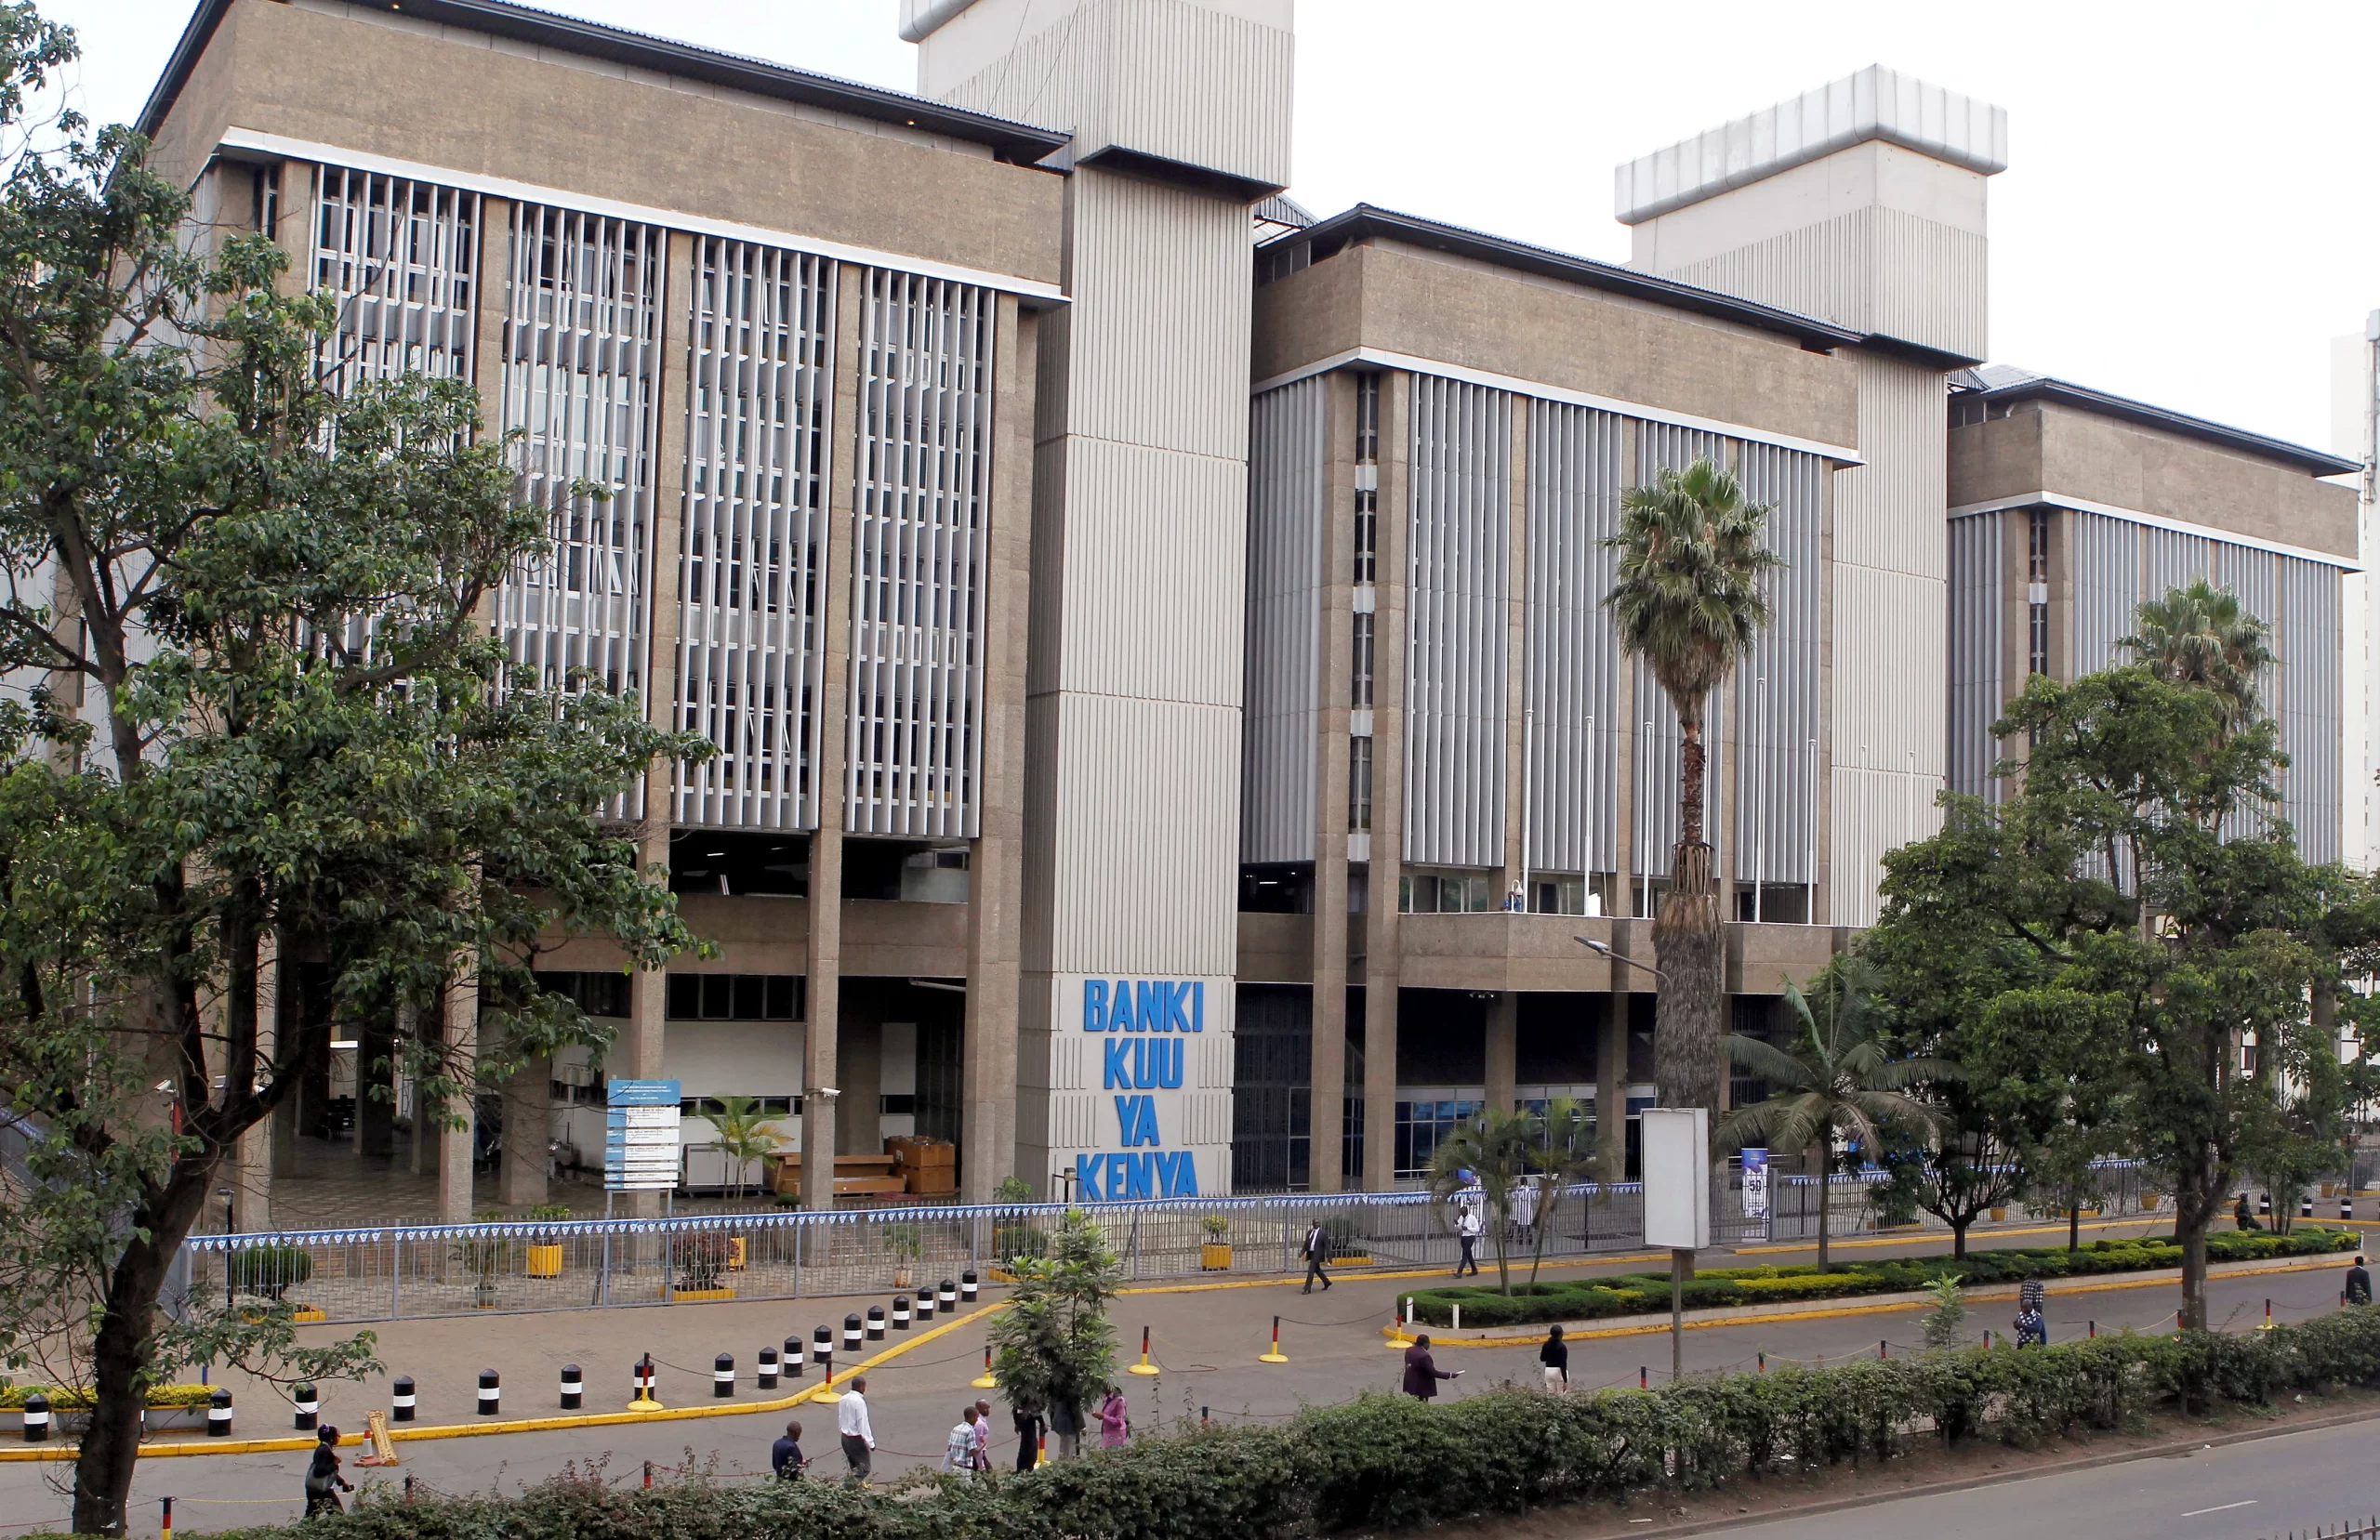
Kenya’s banking sector is undergoing accelerated consolidation, primarily driven by the Central Bank of Kenya’s (CBK) phased increases in minimum core capital requirements.
These regulatory adjustments, aimed at enhancing financial stability, risk absorption, and lending capacity, have compelled smaller institutions to pursue mergers and acquisitions rather than independent compliance through capital raises.
The CBK’s timeline mandates progressive thresholds: KES 3 billion by December 31, 2025, KES 5 billion by the end of 2026, and KES 10 billion by December 2029.
As of early 2026, several smaller banks remain below these levels, creating a capital deficit estimated at billions of Kenyan shillings across the sector. This environment favours strategic combinations that pool resources, achieve economies of scale, and meet compliance more efficiently.
The policy aligns with broader objectives to strengthen financial stability, reduce systemic vulnerabilities, and foster a more competitive landscape capable of supporting larger-scale financing for economic development.
Phased Capital Requirements and Compliance Timeline
The CBK introduced a multi-year schedule for minimum core capital, significantly raising the bar from previous levels. Key milestones include:
- KES 3 billion by December 31, 2025
- KES 5 billion by 2026 (with some sources indicating variations in intermediate steps)
- Further increases leading to KES 10 billion by December 2029
This escalation requires banks to increase core capital through retained earnings, equity raises, or strategic combinations. Reports indicate that, as of late 2025, up to a dozen smaller banks collectively faced a capital deficit of approximately KES 19.8 billion to meet the 2025 threshold, with additional institutions at risk in subsequent phases.

Failure to comply risks regulatory intervention, including potential winding up, underscoring the urgency for affected banks to pursue mergers or seek acquisition partners.
Primary Reasons Driving Mergers Among Smaller Banks
The tightening capital regime creates several pressures that favour consolidation over independent compliance:
- Capital Raising Challenges: Smaller banks often lack access to affordable equity markets or sufficient internal generation capacity. Mergers enable combined entities to pool resources, achieve economies of scale, and meet thresholds more feasibly.
- Operational and Cost Efficiencies: Consolidation reduces duplicated overheads, strengthens balance sheets, and improves risk management, allowing merged institutions to expand lending portfolios and compete more effectively.
- Regulatory Incentives for Stability: The CBK views consolidation positively, as it enhances franchise strength among smaller players and mitigates weaknesses such as limited diversification and vulnerability to economic shocks.
- Market Dynamics: Larger or foreign-backed banks gain strategic footholds through acquisitions, while smaller entities secure survival and growth opportunities.
Recent Examples of Mergers and Acquisitions
The timeline of Kenyan banking M&A from 2012 to 2026 demonstrates a sustained pattern of consolidation, with notable acceleration in recent years due to capital pressures and foreign interest.
- In 2025, Access Bank completed its 100% acquisition of National Bank of Kenya from KCB Group, solidifying its East African presence following earlier transactions such as the acquisition of Transnational Bank.
- In early 2026, the Competition Authority of Kenya approved Zenith Bank Plc’s proposed 100% acquisition of Paramount Bank Limited, subject to employee retention conditions and pending final approvals from the CBK and Nigerian regulators. This marks Zenith’s strategic entry into Kenya.

- Also in January 2026, Nedbank Group submitted an offer to acquire approximately 66% of NCBA Group for around $855 million (in cash and stock), valuing NCBA at 1.4 times book value. The transaction, if completed by late 2026, would accelerate Nedbank’s East African growth.
These examples highlight foreign banks leveraging acquisitions to enter or expand in Kenya, while smaller local institutions seek partners to navigate capital constraints.
Broader Sector Implications
This consolidation wave is expected to result in fewer but stronger institutions, with improved capital positions and greater capacity for credit extension.
It enhances overall sector stability and competitiveness, though it may require careful monitoring to preserve service delivery in niche or underserved markets.
Analyses from sources such as Fitch Ratings indicate that compliance with the 2025 milestone has progressed, yet ongoing pressures toward 2026 and 2029 thresholds will likely sustain M&A activity.
Future Outlook
The tightening of minimum core capital requirements by the Central Bank of Kenya has emerged as the primary catalyst for mergers among smaller banks in 2026.
By necessitating substantial capital augmentation within defined timelines, the policy compels institutions to pursue strategic combinations that enhance financial stability, operational efficiency, and long-term viability.
Recent transactions, including the approved Zenith-Paramount deal and Nedbank’s proposed NCBA stake, exemplify this dynamic, blending regulatory necessity with opportunities for regional expansion.
As of January 26, 2026, continued monitoring of regulatory approvals and integration outcomes will shape the sector’s future trajectory.
For the most current regulatory guidance and transaction details, consult official CBK announcements and credible financial news sources.
Ronnie Paul is a seasoned writer and analyst with a prolific portfolio of over 1,000 published articles, specialising in fintech, cryptocurrency, climate change, and digital finance at Africa Digest News.


Leave a Reply