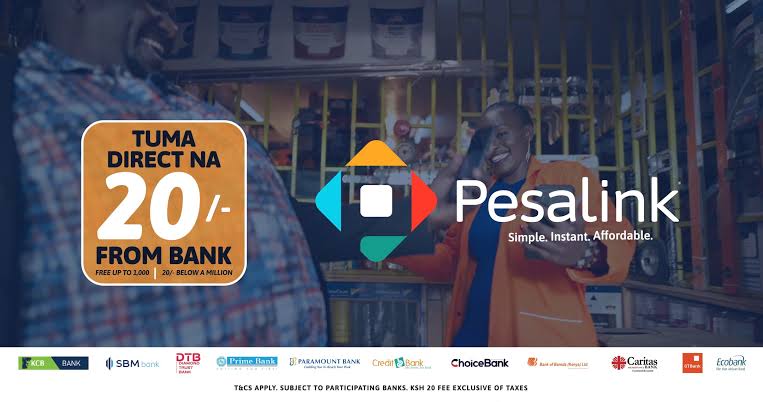
Nineteen Kenyan banks have slashed their transfer fees. This move is part of the Pesalink Tuma Direct na Mbao campaign.
Customers now pay nothing for transfers up to Ksh1,000. Transfers between Ksh1,001 and Ksh999,999 cost a flat Ksh20.
This simple pricing replaces an older tiered model. That model could cost customers up to Ksh250, depending on the amount sent.
Pesalink CEO Gituku Kirika said the pricing overhaul has a clear goal.
He wants digital payments to be affordable, predictable, and easy for everyday customers.
The campaign began with just ten banks in May 2026. It has since grown to nineteen participating banks and microfinance institutions.
Understanding Pesalink Kenya Banks 2026 Participation
Pesalink Kenya banks 2026 adoption has moved quickly. KCB Bank, Diamond Trust Bank, SBM Bank Kenya, and Ecobank were early adopters.
Absa Bank Kenya and Stanbic Bank Kenya joined more recently. Other participants include GT Bank, Paramount Bank, Credit Bank, Bank of Baroda, Choice Bank, and Caritas Microfinance Bank.
Not every major bank has signed on yet. Equity Bank, Co-operative Bank, Standard Chartered, NCBA, and I&M Bank have not adopted the new pricing.
Their absence is notable. These banks serve large customer bases in Kenya.
Whether they eventually join remains an open question for the industry.
READ ALSO:How Paystack and Pesalink Are Streamlining Bank Account Payments for Kenyan Businesses
Why Pesalink Discounted Transfers Kenya Pricing Matters
Pesalink discounted transfers Kenya pricing directly challenges mobile money. M-Pesa has long dominated everyday payments in Kenya.
Its pricing model charges nothing for transfers up to Ksh100. Fees then rise steadily.
A transfer between Ksh501 and Ksh1,000 costs Ksh33. Larger transfers cost even more, up to Ksh108 for the maximum allowed amount.
Pesalink’s flat fee structure now beats M-Pesa on most mid to high value transfers.
A Ksh50,000 transfer to family, for example, previously cost hundreds of shillings through some channels.
Under the new pricing, that same transfer costs just Ksh20. For households sending regular payments, these savings can add up meaningfully over time.
How Pesalink Works Behind the Scenes
Pesalink is not an app people download. It is a payment rail. This rail moves money directly between Kenyan bank accounts.
Customers access it through their own bank’s app, internet banking, or USSD menu.
Many Kenyans have used Pesalink without even knowing its name.
The system is run by Integrated Payment Services Limited. This company is owned by the Kenya Bankers Association.
That ownership structure matters. Kenyan banks collectively own the payment rail.
When they cut fees, they are effectively setting prices for their own shared infrastructure.
Pesalink already processes more than one million transactions each month.
What This Means for Kenya Digital Payments Banking 2026
Kenya digital payments banking 2026 trends show a clear shift. Central Bank of Kenya data reveals ATM cash withdrawals fell to just 3.2 million transactions in February 2026.
That number was 20 million a decade earlier. Kenyans are moving money digitally at a rapid pace.
Banks understand they must offer an experience as smooth as mobile wallets, or risk losing relevance entirely.
Beyond pricing, Pesalink is also planning technical upgrades. Future plans include linking customer profiles to national ID numbers.
This would create a single payment identifier across different banks. Email addresses may also become valid payment destinations.
These changes aim to make bank transfers as simple as sending a text message.
What Comes Next
This pricing war is far from settled. More banks may join the discounted tariff in coming months.
Talks are reportedly ongoing with lenders still outside the initiative. As competition intensifies, banks and mobile money providers will likely keep adjusting their pricing strategies.
For everyday Kenyans, the outcome looks positive either way.
Whether through Pesalink’s flat fees or eventual M-Pesa responses, competition is pushing transfer costs lower across the board.
As Gituku Kirika put it, the goal is simple. Make digital payments cheaper, faster, and easier for the people who use them every day.


Leave a Reply