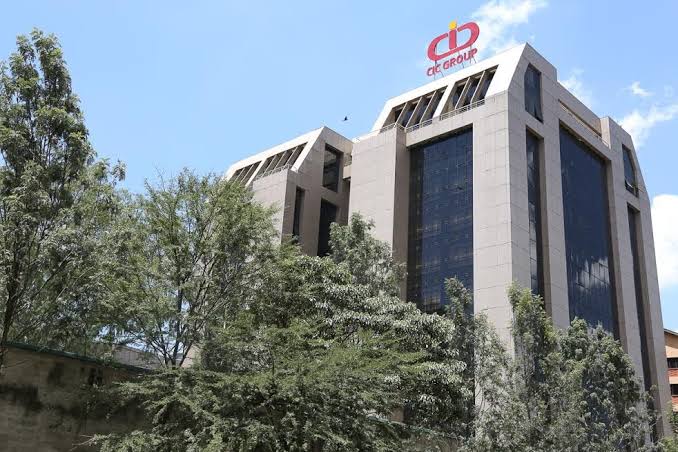
CIC Insurance Group is Africa’s largest cooperative insurer, born from Kenya’s cooperative movement and still majority owned by it today.
It came within a hair of collapse in the early 2000s and rebuilt itself into a listed, regionally diversified insurer whose largest single shareholder is a cooperative society representing well over a thousand member groups. Here’s the full picture.
History and Founding Story
CIC’s roots trace back to 1968, when it began as an insurance agency within the Kenya National Federation of Cooperatives (KNFC), created to serve the insurance needs of Kenyan cooperative societies.
In 1978, it was incorporated and licensed in its own right as Co-operative Insurance Services Limited (CIS).
The company’s early decades were shaped by strong support from the cooperative movement, which fuelled rapid growth.
But by the early 2000s, CIC (then still using its earlier name) was on the verge of collapse: it could not meet the government regulator’s minimum share capital requirements, and even a KSh90 million grant from the International Cooperative and Mutual Insurance Federation, plus international consultants, could not immediately turn things around. A recovery effort over the following years pulled the company back from the brink.
In 1999, the business was renamed the Co-operative Insurance Company of Kenya (CIC) as part of a market repositioning ahead of regional expansion into Uganda and Sudan.
In 2010, it rebranded again to CIC Insurance Group Limited, in preparation for a demerger of its life and general insurance operations, which was completed in 2011 with the formation of CIC Life Assurance Limited, CIC General Insurance Limited, and CIC Asset Management Limited as distinct entities under the group umbrella.
On 19 July 2012, CIC Insurance Group listed its shares by introduction on the Nairobi Securities Exchange, at an opening price of KSh3.50, turning more than 3,000 existing shareholders, including over 1,350 cooperative societies and individuals, into instant public market investors.
The group has since expanded into South Sudan, Uganda, and Malawi, and in 2026 launched CIC IMPACT, a microinsurance business aimed at Kenya’s underserved informal sector.
Core Business Lines / Revenue Streams
CIC operates as a diversified insurance and financial services group, structured around distinct subsidiaries for its major business lines.
- General insurance: Motor, marine, agriculture, property, fire, personal accident, travel, and other short term covers for individuals and businesses, offered through CIC General Insurance Limited. This remains a core earnings driver, with the Kenyan general insurance business posting a 33% rise in pre-tax profit in the first half of 2026.
- Life assurance: Group life, family protection, loan guard insurance, pensions, and endowment plans through CIC Life Assurance Limited.
- Asset management: CIC Asset Management offers equity, balanced, fixed income, and money market fund management to institutional and retail clients, a business that has been growing quickly, with revenue up 25.2% to KSh1.04 billion in the first half of 2026 on the back of rising assets under management.
- Microinsurance: The newly launched CIC IMPACT targets Kenya’s large informal sector with accessible, lower cost insurance products.
- Property and other income: The group has periodically generated notable one off income from land sales and other property related activity, including KSh962 million in land and pharmaceutical sales revenue recorded in the first half of 2026 alone.
- Regional subsidiaries: Operations in Uganda, South Sudan, and Malawi supplement the core Kenyan business, with CIC South Sudan posting particularly strong growth (insurance revenue up 71%) in the first half of 2026.
Competitive Position in Its Industry
CIC describes itself as Africa’s largest cooperative insurance company, and it has built a genuinely distinctive market position around Kenya’s roughly 1,550 registered cooperative societies and their millions of members, a customer base few other insurers can access as directly.
It has also historically targeted small and medium sized enterprises, a segment management has said accounts for much of the company’s growth.
Recent results show a group leaning heavily on investment returns and diversification to offset pressure in its core underwriting business.
CIC issued a profit warning ahead of its full year 2025 results, citing rising claims pressure, and full year 2025 profit came in well below prior year levels even as insurance revenue grew 12% to KSh29.5 billion.
The first half of 2026 showed a stronger recovery: net profit jumped 70.3% to KSh1.09 billion, driven substantially by a 43.9% rise in investment returns to KSh3.96 billion, alongside solid growth in its asset management and Kenyan general insurance units.
CIC’s main listed rivals in Kenyan insurance include Britam Holdings, Jubilee Holdings, and Sanlam Allianz Holdings Kenya.
Where CIC differs is its cooperative movement ownership and distribution advantage, and its comparatively smaller scale, with total assets of about KSh81.7 billion as of mid-2026, a fraction of some larger rivals.
READ ALSO:Inside the NSE: Jubilee Holdings (JUB)
Ownership Structure
CIC is unusual among NSE listed insurers in that its controlling shareholder is not a private founder, foreign fund, or the state, but a cooperative society representing the movement that created it.
- Co-operative Insurance Society Limited (CIS): The dominant shareholder, historically holding a strategic stake of around 74.3% at listing, a figure that has since diluted somewhat through rights issues and private placements but remains the controlling stake. CIS itself represents the cooperative societies and individuals that make up Kenya’s cooperative movement.
- Co-operative Bank of Kenya: A significant institutional shareholder in its own right, with a stake that has fluctuated over time (reported as high as 26.54% following a 2011 private placement, and capped at 25% under Kenyan insurance regulations that limit non-insurance institutional shareholders to a maximum quarter stake).
- Individual and management shareholders: Notably, Co-operative Bank’s long serving Group Managing Director, Dr. Gideon Muriuki, has been CIC’s largest individual shareholder for over a decade, a reflection of the close business ties between the bank and the insurer. Other individual shareholders include board members and current and former executives of CIC itself.
- General public and institutional investors: The remainder is held by the roughly 24,000-strong shareholder base of pension funds, fund managers, and retail investors trading the stock on the NSE.
Why It’s Listed on the NSE Specifically
CIC’s 2012 NSE listing was structured as a listing by introduction, meaning the company did not raise fresh capital through the transaction.
Group CEO at the time, Nelson Kuria, explained that CIC already had sufficient funds to run its programmes; the purpose of listing was instead to give its more than 3,000 existing shareholders, cooperative societies and individuals who had held illiquid, informally traded shares for years, a formal, transparent market on which to trade their stakes and finally realise the value they had built up.
That structure reflects something distinctive about CIC among NSE listed companies: it wasn’t a government privatisation, a family business going public, or a foreign entrant seeking local capital.
It was, fundamentally, a cooperative sector institution formalising decades of member ownership into a tradable public security, giving Kenya’s cooperative movement, an economic force touching well over 14 million members according to the group’s own figures, a direct stake in a listed financial services company.
Current Stock Price
CIC’s share price has traded at around KSh4.96 in recent data, with the stock cited as up 82.47% over the period tracked, reflecting a broader rally across NSE listed insurers through 2025 and 2026.
That puts the company’s market capitalisation at roughly KSh14.3 billion. The stock listed at KSh3.50 in 2012 and has traded well below that in some periods since, including lows around KSh1.90 to KSh2.70 in past cycles, so the recent rally represents a meaningful recovery.
Share prices move daily. For a live quote, check the NSE’s official market data page or a licensed brokerage platform before making any decisions.
How to Buy CIC Insurance Group Shares
You don’t need to be in Kenya to buy CIC shares; it can be bought locally or from abroad:
- Open a CDS (Central Depository System) account. This is Kenya’s electronic share registry account, required to hold any NSE listed stock. It’s opened through a licensed stockbroker or investment bank.
- Choose a licensed NSE stockbroker or investment bank. Examples include firms like Standard Investment Bank, AIB-AXYS Africa, Genghis Capital, and Faida Investment Bank. A full list of licensed trading participants is available on the NSE website.
- Fund your trading account via bank transfer, mobile money (M-Pesa is widely supported), or card, depending on the broker.
- Place an order for CIC through the broker’s trading platform, app, or by instructing your broker directly, specifying the number of shares or amount you want to invest.
- For non resident and diaspora investors, several online platforms (such as mystocks.africa and similar cross border brokerages) let you open an account remotely, fund it in USD or your local currency, and buy NSE listed shares like CIC without needing an in country presence, though you should confirm licensing and custody arrangements before using any platform.
- Hold and track. Shares are held electronically in your CDS account. CIC has a consistent, though modest, dividend record, having declared a final dividend of KSh0.13 per share for the 2025 financial year, the same level it has held for several consecutive years, paid out directly to your linked bank account.
This profile is for informational and editorial purposes and is not investment advice. Stock prices, especially, change constantly, so always verify current figures with the NSE or a licensed broker before making any investment decision. Other figures reflect the most recent publicly reported data as of 2026 and may change with new financial disclosures.



Leave a Reply