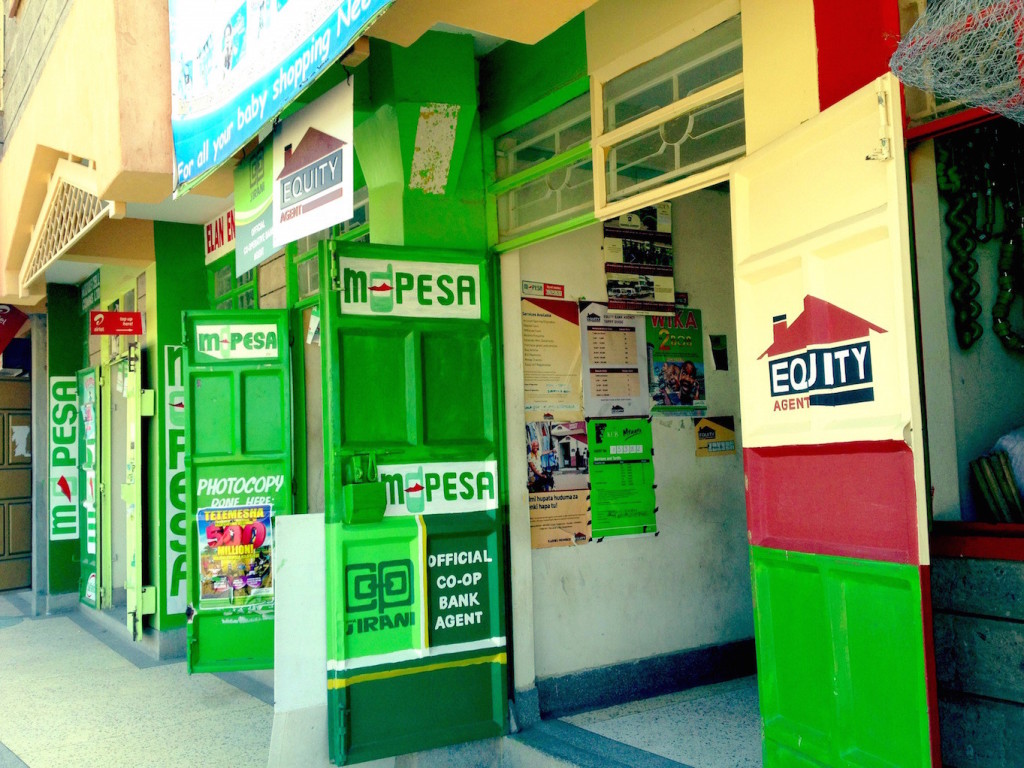
In Kenya’s dynamic financial landscape, M-Pesa and traditional bank accounts are not rivals but complementary tools.
M-Pesa reshaped access to financial services with its vast agent network and instant transactions, while banks offer depth for savings, credit, and larger-scale operations.
Most savvy users integrate both for optimal efficiency and cost control.
Current Key Facts (as of 2026)
M-Pesa Limits (Safaricom Official):
- Maximum account balance: KSh 500,000
- Maximum per transaction: KSh 250,000
- Maximum daily transaction value: KSh 500,000
- Deposits are free; small sends (up to KSh 100) are often free.
M-Pesa Transaction Fees (Selected Examples, Customer Charges):
- Send to other M-Pesa users/Pochi La Biashara/Business Till (KSh 101–500): KSh 7
- (KSh 1,501–2,500): KSh 33
- (KSh 20,001–250,000): KSh 108
- Agent withdrawal (KSh 50–100): KSh 11; higher tiers up to KSh 309 for larger amounts
- ATM withdrawal and other services have separate tariffs.
Bank Transfers via PesaLink: Fees are typically lower for interbank moves (often KSh 0–KSh 250 depending on the bank and amount, with many offering free or minimal charges up to certain thresholds). Higher limits are common for bank-to-bank transfers.
Additional M-Pesa Features:
- Pochi La Biashara: For small businesses/vendors.
- M-Shwari/Fuliza: Savings, loans, and overdraft options.
- Lipa na M-Pesa: Merchant and bill payments.
Advantages and Disadvantages
M-Pesa Strengths:
- Unparalleled accessibility via agents (far more than bank branches), ideal for rural or unbanked users.
- Instant P2P transfers, bill payments, and merchant transactions.
- No traditional bank account required initially; works on basic phones via USSD (*334#) or the app.
- Quick cash-in/out and emergency credit via Fuliza.
M-Pesa Limitations:
- Cumulative fees on frequent or larger transactions and withdrawals.
- No (or minimal) interest on balances.
- Daily/per-transaction limits (though significantly raised).
- Security depends on PIN and phone protection.
Bank Account Strengths:
- Often lower fees for internal or PesaLink transfers.
- Interest on savings accounts.
- Higher limits for large transactions, salaries, and international transfers.
- Access to structured loans, overdrafts, investments, insurance, and credit history building.
- Robust record-keeping and security features (cards, apps, alerts).
READ ALSO:Does Safaricom My OneApp Work Outside Kenya? Complete FAQ
Bank Account Limitations:
- More documentation and potential minimum balances or fees.
- Fewer physical access points in remote areas.
- Potentially slower for very small, urgent informal transfers.
Recommended Use Cases
Prioritise M-Pesa for:
- Everyday small P2P transfers to family, friends, or informal workers (especially amounts under KSh 100, often free).
- Merchant payments (Lipa na M-Pesa) and utility bills.
- Cash-in/cash-out in areas with limited bank presence.
- Micro-business operations via Pochi La Biashara or Till.
- Instant needs or short-term credit (Fuliza/M-Shwari).
Prioritise Your Bank Account for:
- Receiving salaries, pensions, or formal business inflows.
- Holding larger savings (to earn interest and reduce exposure).
- Large transfers or payments (cheaper via PesaLink).
- Loans, investments, and building formal credit.
- International remittances or high-value transactions.
Hybrid Strategy (Best for Most Kenyans):
- Link your bank account to M-Pesa for seamless movement of funds in both directions.
- Maintain a modest “float” in M-Pesa for daily convenience.
- Sweep larger amounts or savings to your bank account.
- Use bank apps or PesaLink for bulk/inter-bank transfers; top up M-Pesa as needed.
- For businesses: Accept payments via M-Pesa Till/Pochi and regularly transfer to the bank for security and lower costs.
Practical Tips
- Always verify the latest fees and limits directly via *334# (M-Pesa), your bank’s app/USSD, or official websites, as tariffs can be updated.
- Enable transaction alerts and use strong PINs/biometrics for security.
- For cost optimisation, compare sending via PesaLink versus direct M-Pesa for mid-sized amounts.
- Businesses should reconcile accounts regularly to track fees and cash flow.
M-Pesa excels in speed, reach, and inclusivity for daily and informal transactions, while bank accounts provide the foundation for financial growth and stability at scale.
By strategically using both leveraging interoperability through PesaLink and linked services, Kenyans can minimise costs, maximise convenience, and build long-term financial health.
Individual needs vary based on transaction volume, location, and goals; consider consulting a financial advisor for personalised strategies.
This article is based on official Safaricom tariffs and public banking information as of mid-2026. Fees and limits are subject to change; always confirm with providers.


Leave a Reply